· 5 min read
The IMF Warns About an AI Correction. Who Else Could Feel It?
A potential AI market correction could spread through debt and portfolios. This is not a crash forecast.
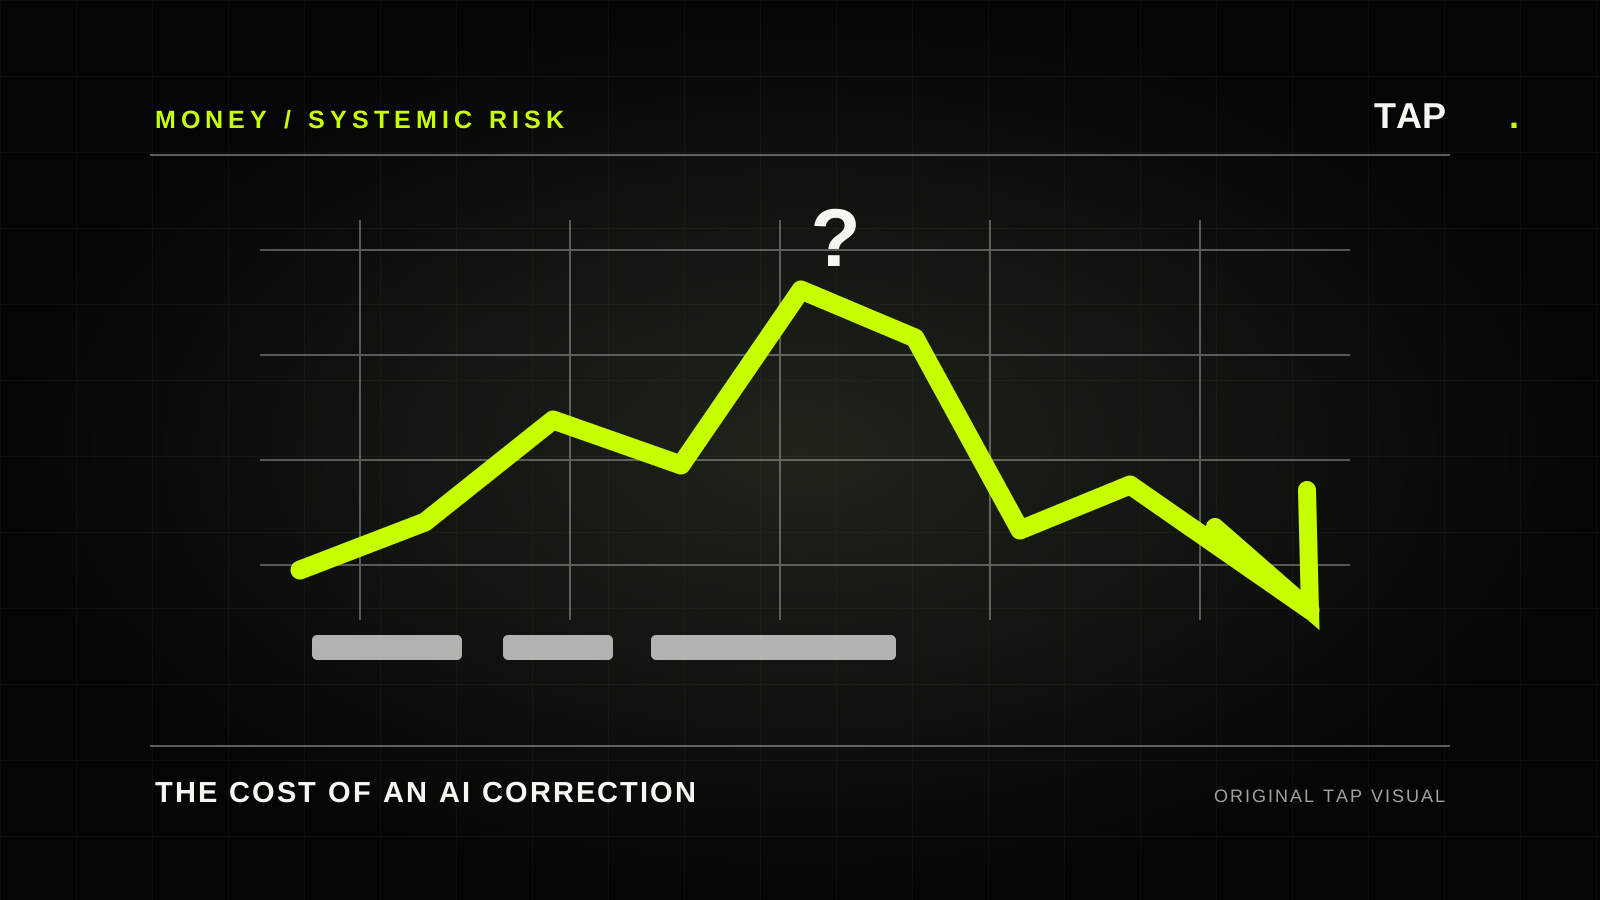
Illustrative chart only, not real prices or IMF numerical projections. · TAP original editorial artwork
The headline almost writes itself: the International Monetary Fund is warning about an AI market correction. But the more useful question is how far a disappointment in AI profits could travel beyond technology shares.
On October 13, the IMF said financial markets remained resilient while warning that an AI-related selloff, rising government-bond yields and major cyber incidents could become sources of stress. These are possible scenarios, not predictions of an imminent collapse.
A useful technology can still be an expensive investment
AI systems can become more capable even while some companies fail to earn the returns investors expect. Better technology does not guarantee that every data center, chip order or business model justifies its current valuation.
When investors pay for profits years into the future, disappointing results can change prices quickly. The IMF's concern is not merely the price of one technology stock but the way concentrated expectations connect to other markets.
The hidden link is borrowing
Reuters reported that the IMF found major cloud and AI infrastructure operators now account for about 10% of global investment-grade bond issuance, compared with under 1% in 2024. This figure requires final confirmation in the full report before publication.
A business financed largely with its own cash faces one kind of setback if demand disappoints. A borrower must still service debt when expected profits weaken. Bondholders, lenders and funds may then reassess risk. That is one channel through which an AI correction could reach investors outside the technology sector.
Why the effects might reach ordinary investors
People do not need to own an AI company directly to be exposed to broad market shifts. Retirement portfolios, insurance investments and diversified funds may hold shares or bonds connected to the sector. If investors reduce risk together, selling pressure can spread to other assets.
This is not a claim that pension losses or a credit crunch are inevitable. The IMF's stress tests suggest the banking system remains broadly resilient, while warning that weaker banks and non-bank lenders could amplify shocks. Financial resilience depends on these links.
The question beyond the headline
The IMF also warned about sovereign bond yields and cyber incidents. Shocks do not necessarily arrive one at a time. Higher borrowing costs can complicate refinancing when asset prices are already under pressure.
TAP's overlooked question is not whether AI works. It is who holds the financial risk if expected returns disappoint. How much borrowing supports the boom? Who owns the debt? Which lenders can absorb losses? Those questions matter more than treating a risk assessment as a prophecy.
Source note: The October 13 IMF briefing is available directly. IMF risk scenarios are not forecasts of a certain crash.